Behavioural coaching
Wendy reads your full money picture, learns how you actually spend, and coaches you in small daily moments rather than one guilt-trip a month.
Meet Lertha
We are building the behavioural layer for personal finance in Africa: the part that notices what you actually do with money, explains it without judgement, and helps you change it.
₦0
of your money we hold, move or invest. Ever.
NDPC
registered data controller, NDPC/DCP/14612
3
ways in at launch: iPhone, Android and the web
The waitlist is open and the app is in private testing. We would rather say that plainly than dress a launch date up as a number.
What Lertha is
Lertha sits beside the banks and products you already use. It reads what is happening, tells you what it means, and helps you build the habits that change the number at the end of the month.
Wendy reads your full money picture, learns how you actually spend, and coaches you in small daily moments rather than one guilt-trip a month.
Goals you commit to, caps you set yourself, and nudges that arrive before the money leaves, not after the statement lands.
When you need a savings, insurance or credit product, Lertha points you at licensed, regulated providers. The money goes to them, never through us.
What Lertha is not
Lertha is regulated where it needs to be and deliberately powerless where it does not. The clearest way to say that is to list what we are not.
Mission
Written down early, because it is the thing every later decision gets measured against.
To help Africans build healthier financial habits and make smarter financial decisions, through behavioural intelligence, accountability and guidance they can trust.
Vision
To become Africa’s most trusted behavioural finance platform: where good financial behaviour becomes measurable credibility, and that credibility opens doors that a salary slip never could.
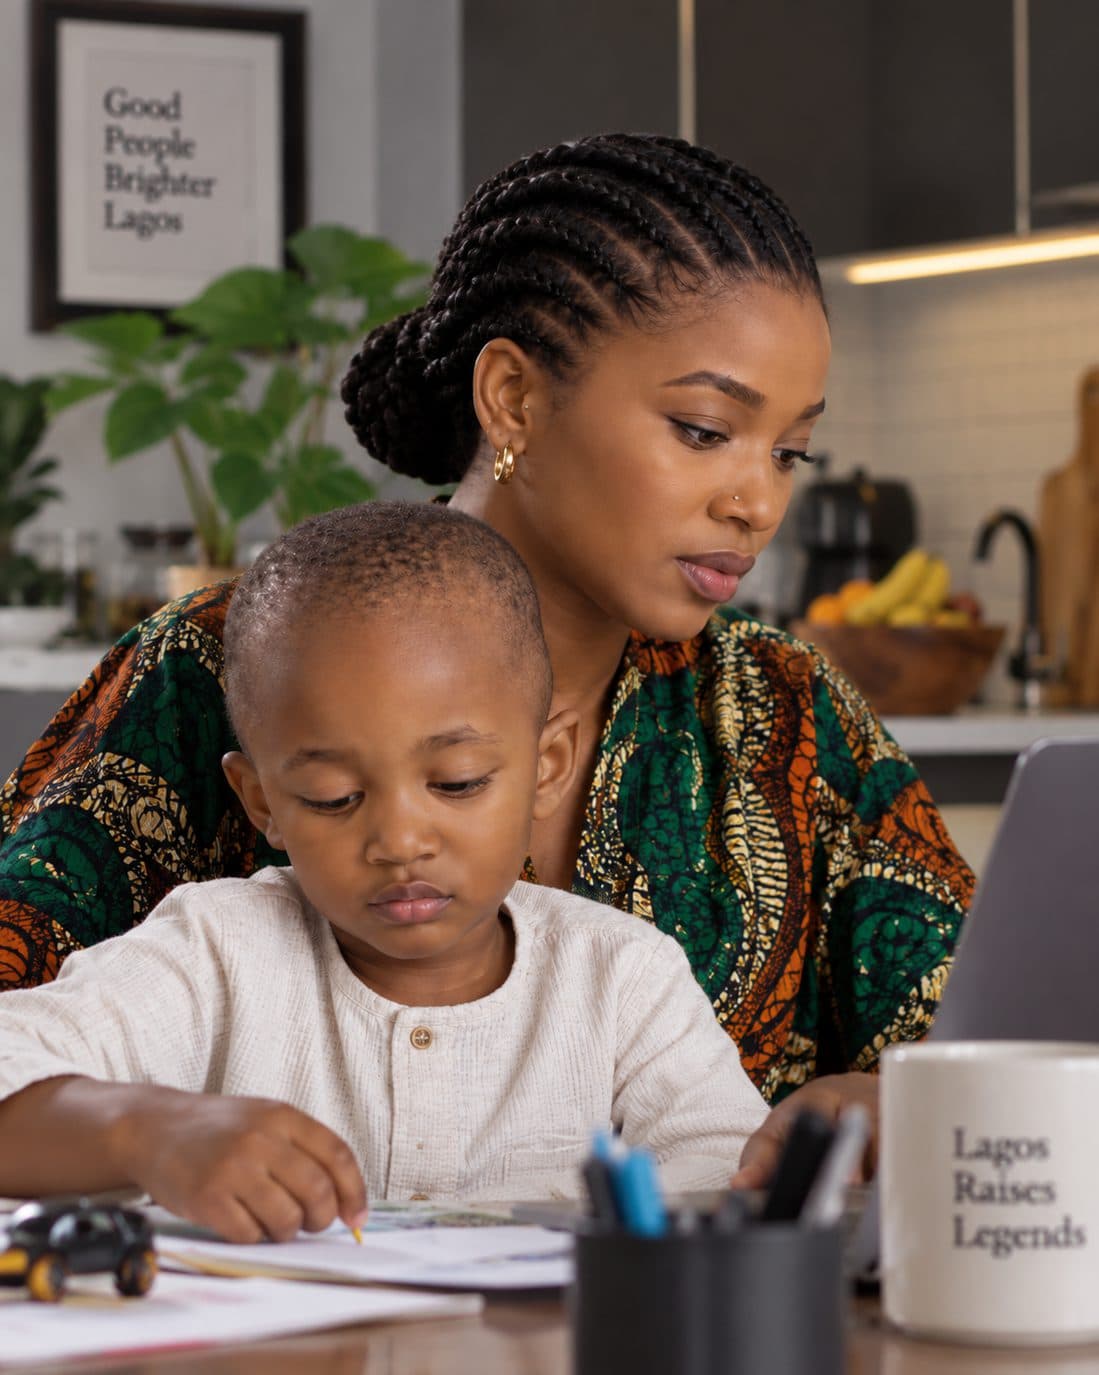
The people we are building for: salaried, self-employed, supporting family, and making hundreds of small money decisions a month with no one in their corner.
Coaching is the wedge, not the destination. Each phase only earns the next one by working.
Help people understand their own financial behaviour.
Spending intelligence, diagnostics, the Freedom Score, daily coaching, plain-English literacy.
How we would know: You consistently know where your money went, without opening a spreadsheet.
Turn understanding into habits that hold.
Goal accountability, emergency funds, savings commitments, automated nudges before the spend.
How we would know: Savings become consistent and impulse spending falls.
Connect people to the right financial product at the right moment.
Matching into licensed savings, insurance and credit partners, with the reasoning shown.
How we would know: People end up in better products because of guidance, not advertising.
Make good behaviour count for something.
Behavioural scoring, savings consistency, reliability patterns: a portable financial identity.
How we would know: Discipline improves access to credit, cover and opportunity.
Phases two to four are intent, not a release schedule. Dates go in the app, never on a marketing page.
Coaching is free during early access. Lertha earns from the licensed providers it introduces you to, never from your data: we do not sell it, and we will not.
Two rules come with that, and we hold ourselves to both. A partner fee never decides what Wendy recommends, and when something is a partner product, you will be told so on the screen where you choose it.